Professional-services firms sell expertise, time, judgement, and outcomes rather than products that can be counted in a warehouse. That makes financial management especially important. A firm may have a strong pipeline, skilled staff, and profitable engagements on paper, yet still face pressure if work is delivered slowly, invoices are delayed, or growth consumes cash faster than clients pay.
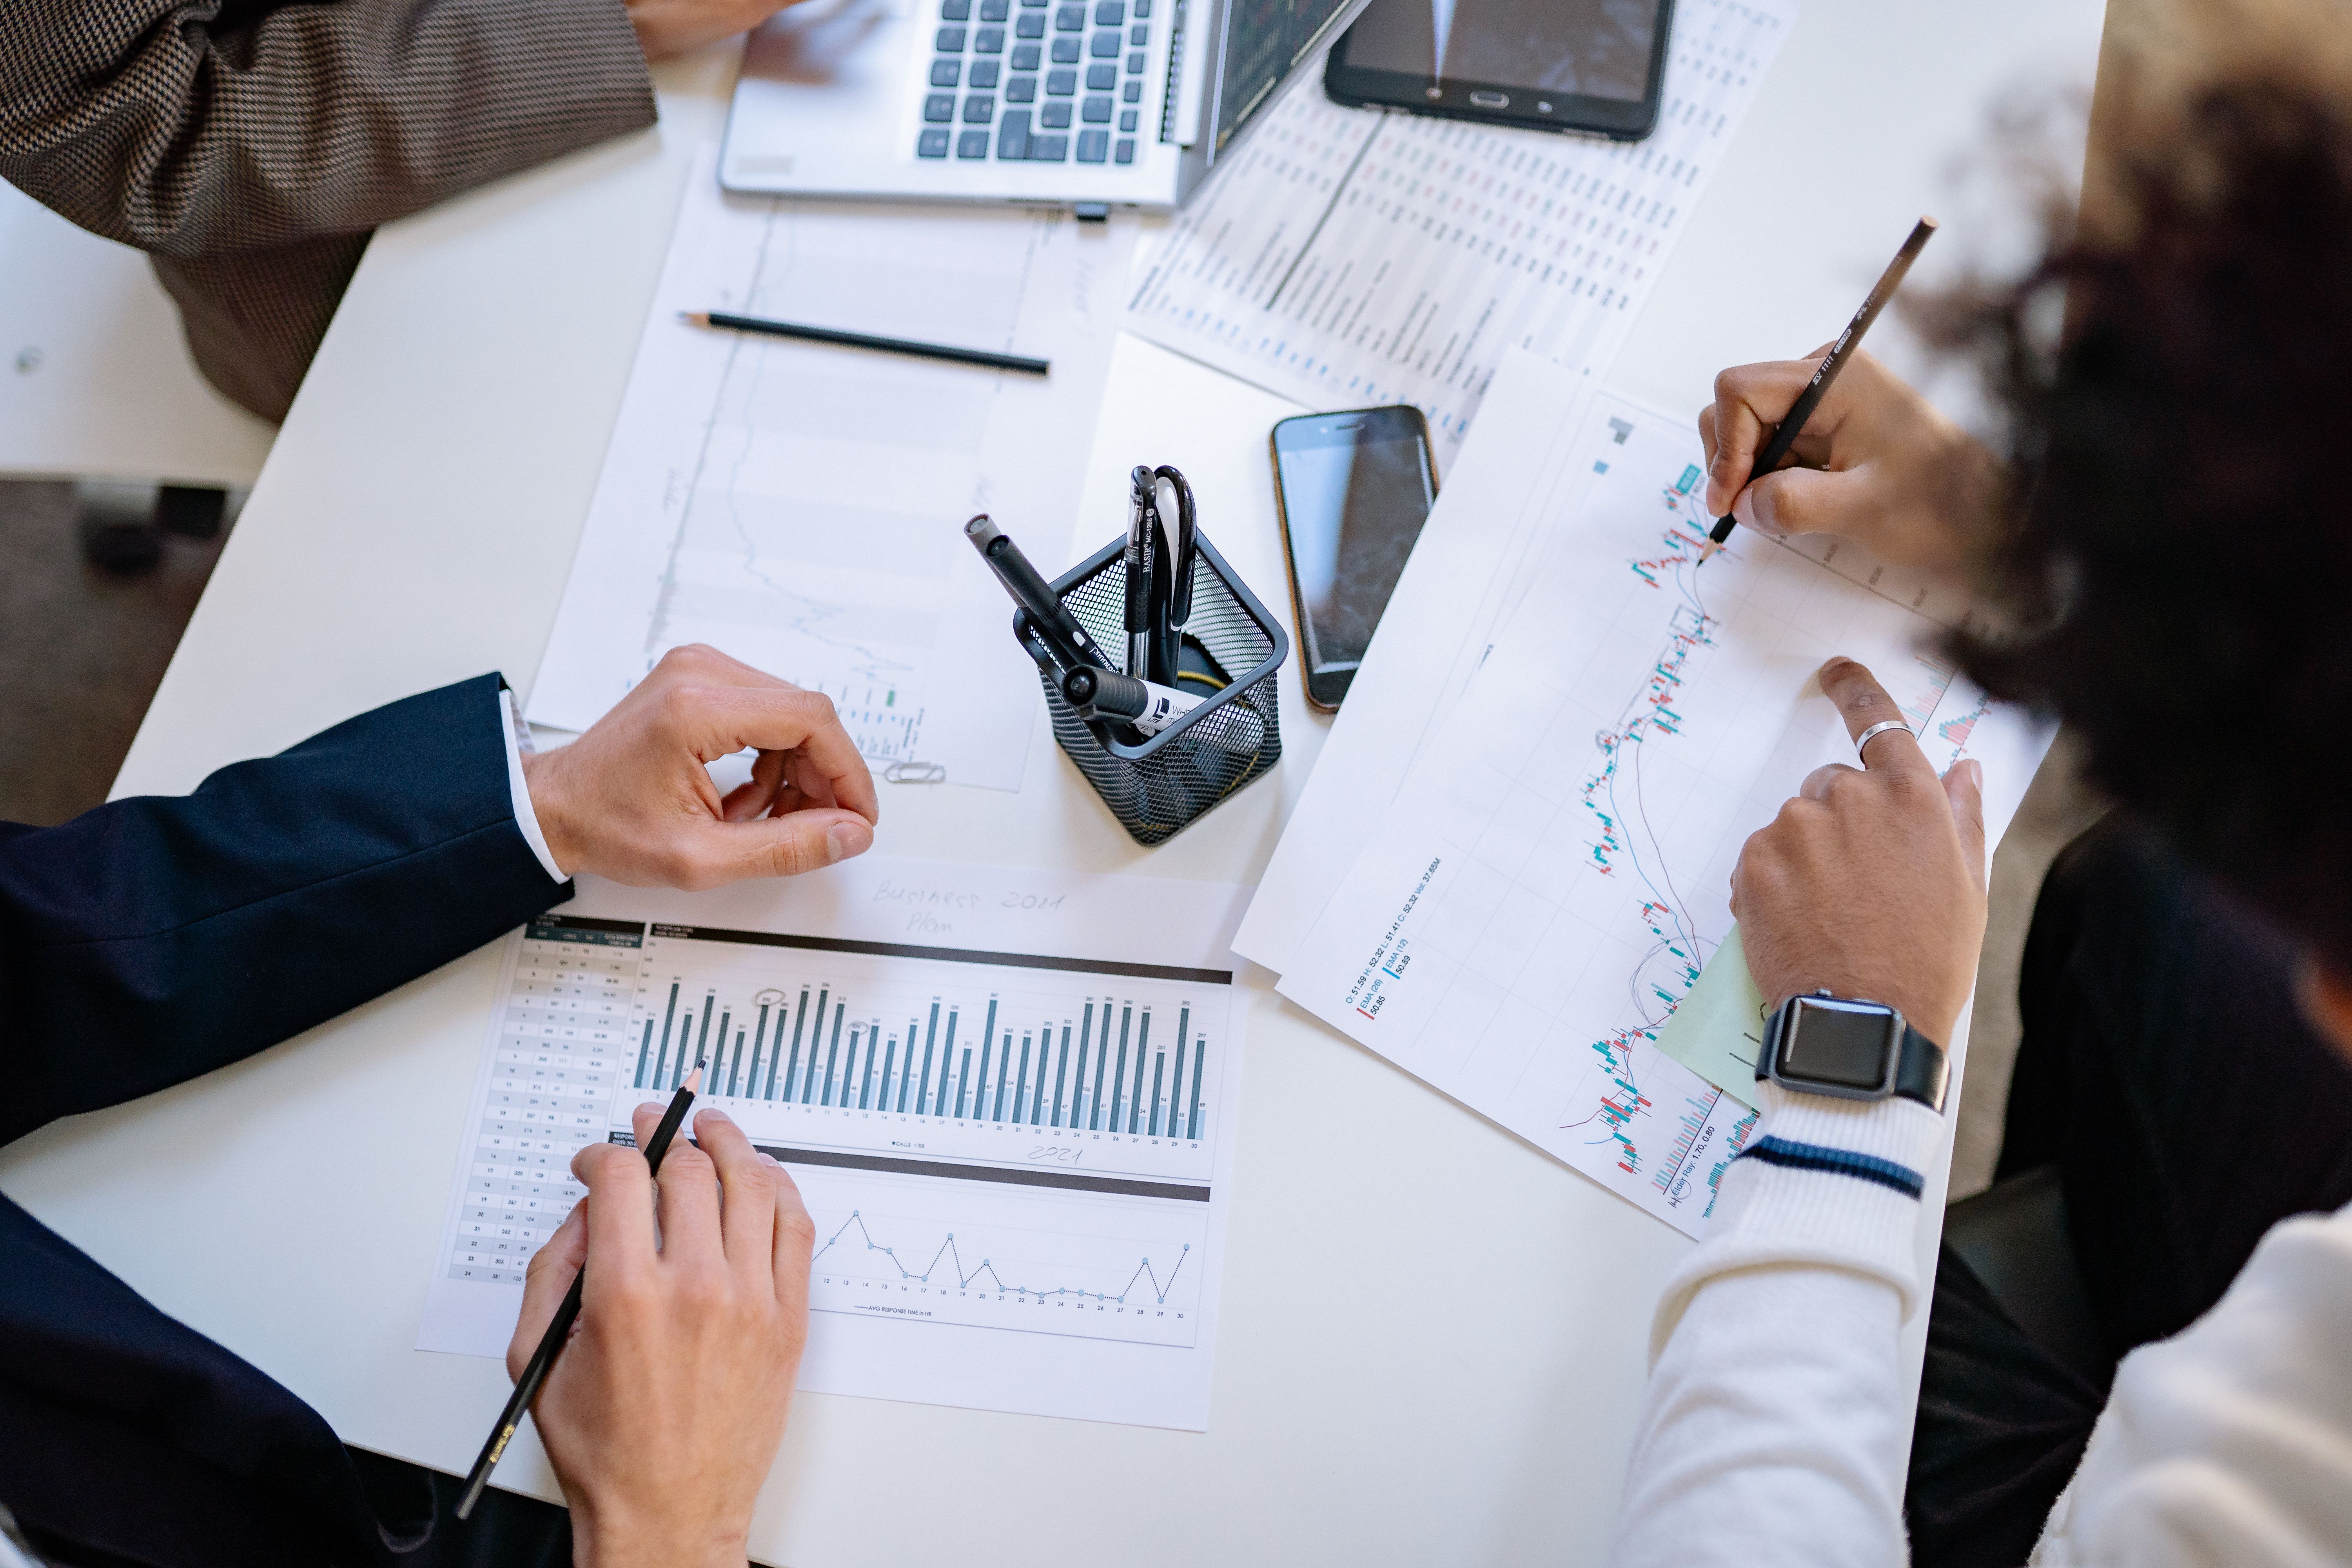
In this context, financial management is more than bookkeeping. It is the connected process of planning revenue and costs, setting sustainable prices, monitoring performance, managing working capital, meeting obligations, and using reliable information to decide what the firm should do next. The International Federation of Accountants’ guidance on practice KPIs describes monitoring performance against budgets and relevant peers as a way to understand the drivers of practice profitability.
The business model makes cash timing critical
Many professional-services businesses incur costs before they receive payment. Salaries, software, premises, insurance, training, subcontractors, and marketing may need to be paid while an engagement is still underway. In some practices, a substantial amount of work must also be completed before an invoice can be raised.
This creates an important difference between profitability and liquidity. Profit measures whether income exceeds costs over an accounting period. Cash flow measures when money actually enters and leaves the bank account. A profitable project can therefore create a short-term funding requirement if its costs are paid now and its invoice is settled later.
Government guidance for company directors describes cash flow as money moving into and out of a company and identifies insufficient cash as a significant business risk, including during periods of growth. For a professional-services firm, a rolling cash forecast can show when payroll, tax, supplier payments, loan commitments, or planned investment may coincide.
Financial management turns activity into useful information
A monthly profit-and-loss statement is necessary, but it is rarely enough on its own. Leaders also need to understand the operational events behind the numbers: how much work has been sold, how much has been delivered, what remains unbilled, which invoices are overdue, and how much capacity is available.
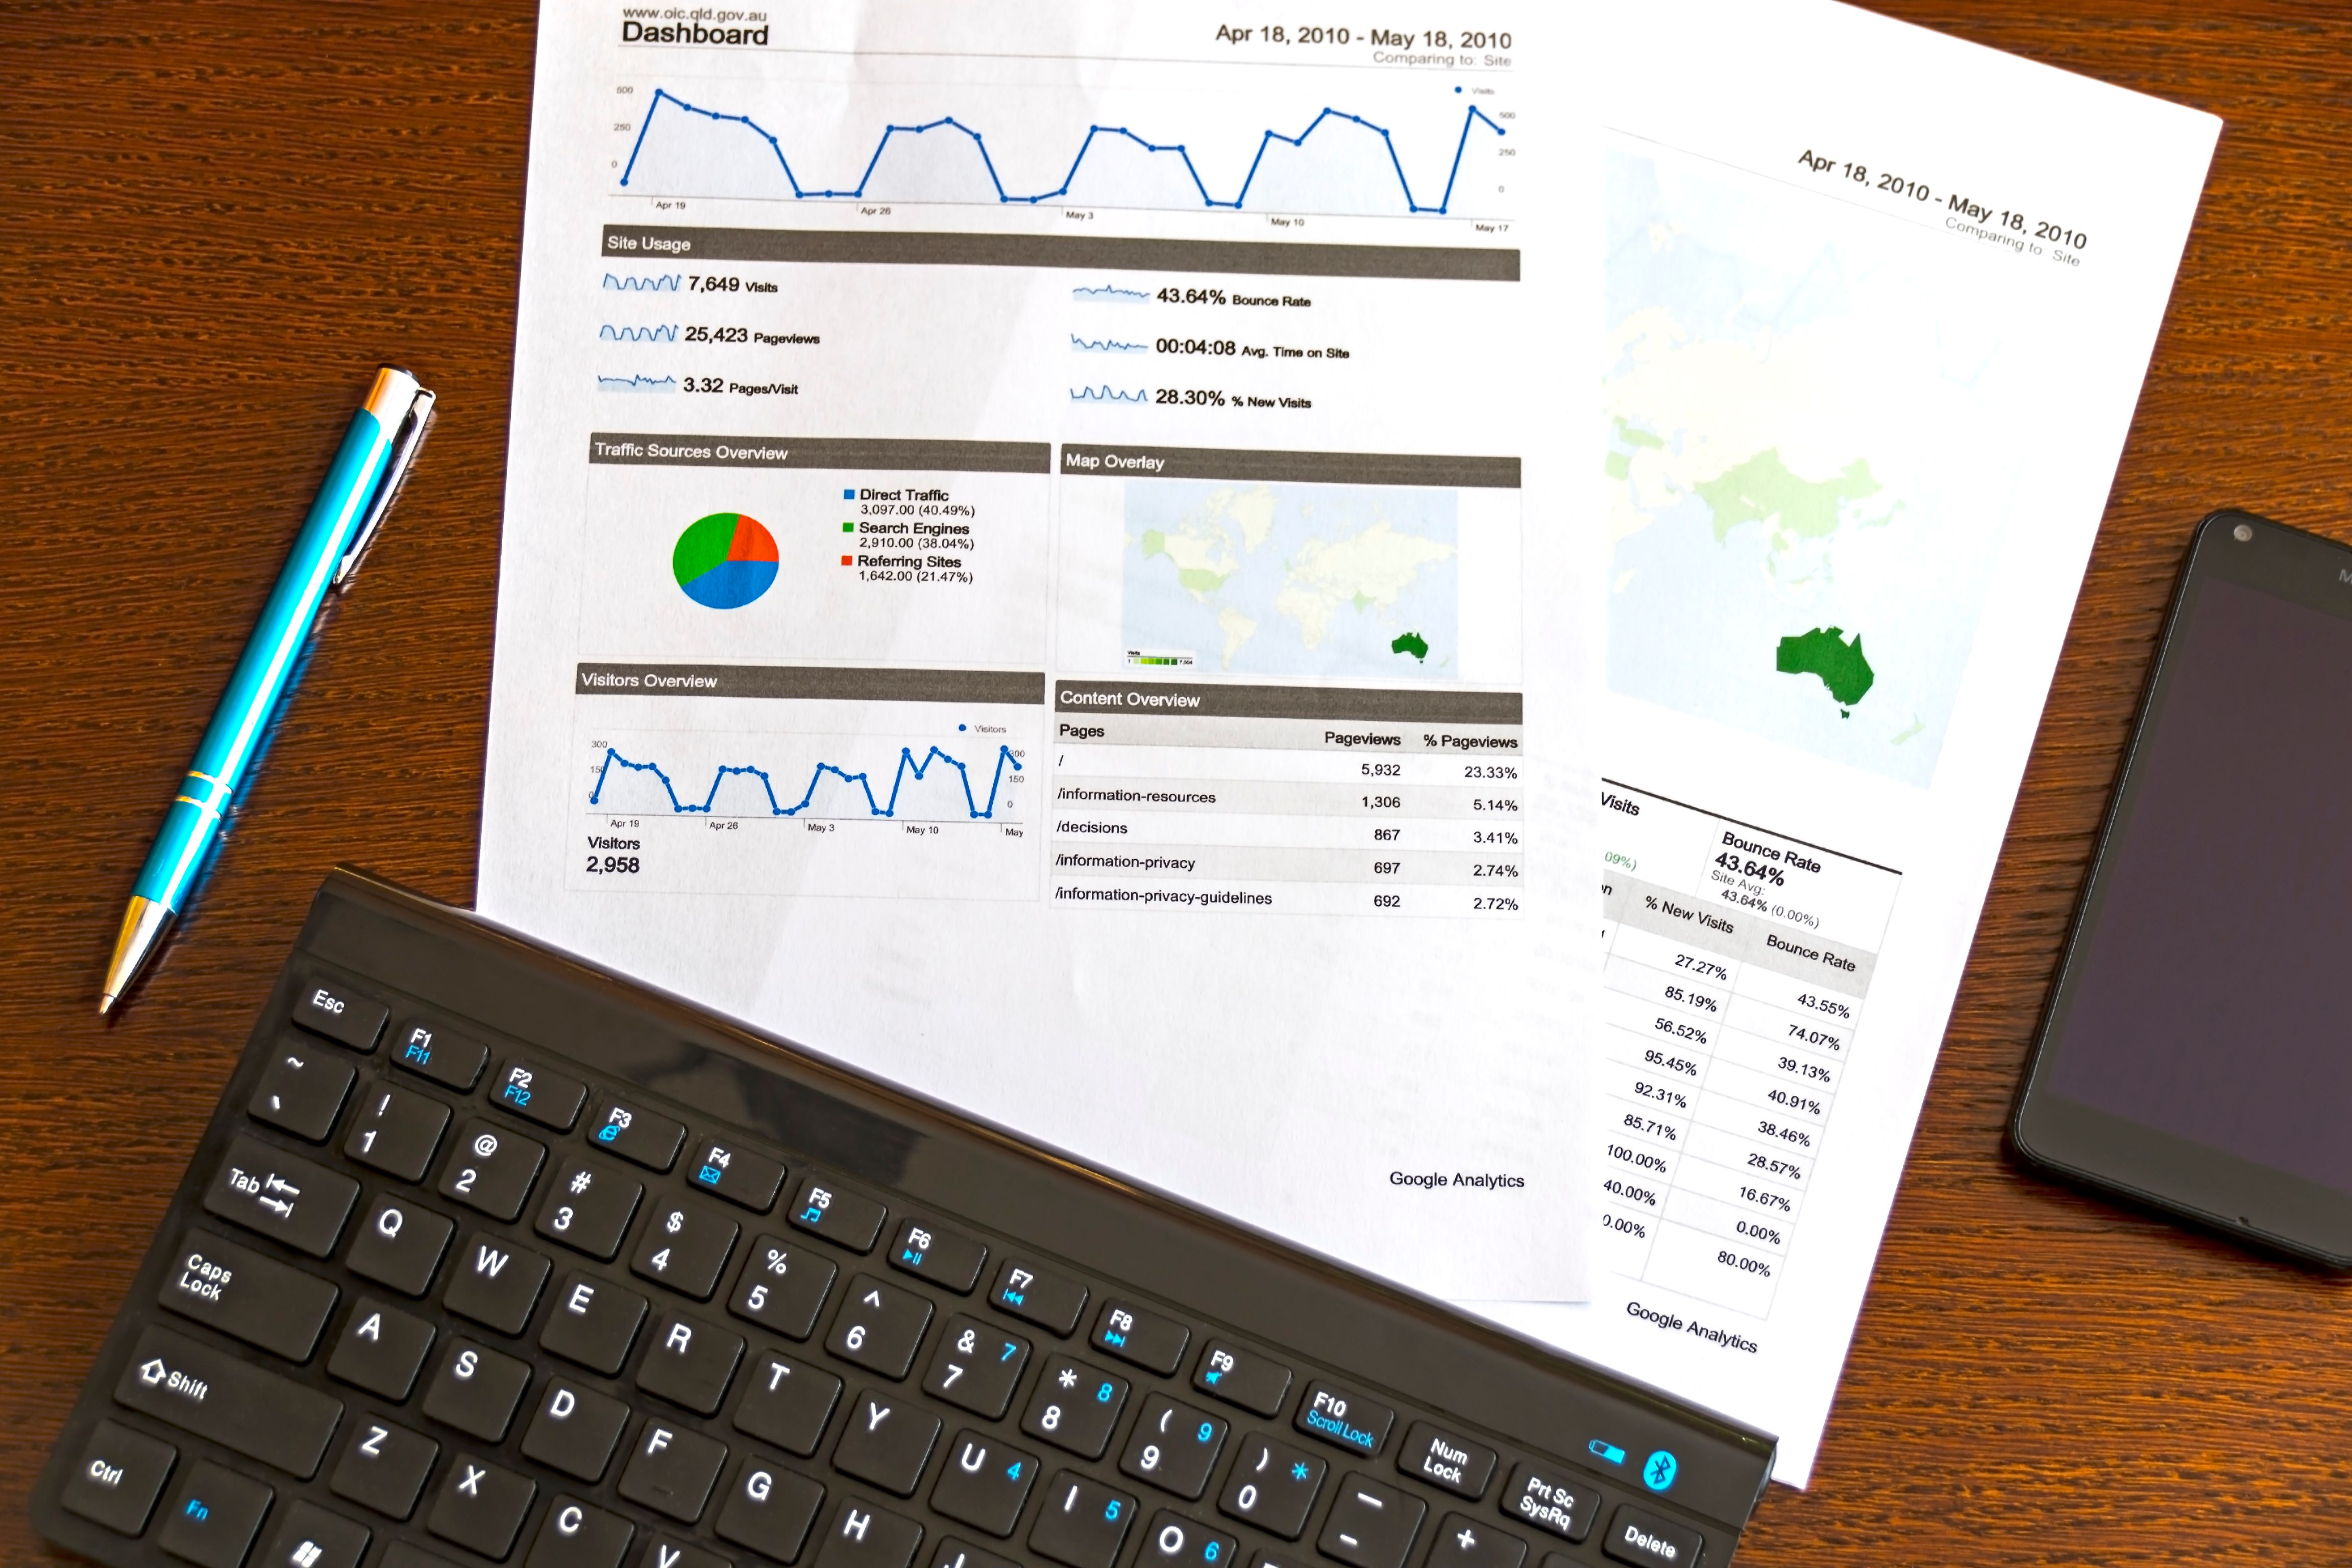
A useful management pack might include:
- Revenue by service line, client group, or engagement type
- Gross margin and contribution after direct delivery costs
- Utilisation, billable time, or another relevant capacity measure
- Fee recovery or the difference between work performed and fees billed
- Work in progress and debtor days
- Cash received, cash committed, and forecast closing cash
- Actual results compared with budget and the latest forecast
The point is not to produce a larger report. It is to identify a small set of measures that answer practical questions. Are engagements being priced with enough room for delivery and overhead? Is the team spending time on work that can be billed? Are invoices being issued promptly? Is a rise in revenue also producing additional cash?
Pricing protects quality as well as margin
Pricing is one of the earliest financial decisions in an engagement. A rate or fixed fee must account for the expected delivery effort, supervision, technology, overhead, risk, and the level of service promised to the client. If those elements are not understood before work begins, the firm may need to absorb additional effort or renegotiate scope later.
The ICAEW guidance on fees and charge-out rates notes that under-recovered assignments can be hidden in a conventional profit-and-loss view. That is why firms should compare quoted or agreed fees with actual time, costs, and changes in scope, not only with total revenue.
Clear engagement letters and proposals support this process. They can define the service, assumptions, deliverables, exclusions, payment schedule, and approach to additional work. This is commercially useful and helps both parties understand what the agreed price covers.
Cash discipline starts before the invoice
Cash management is influenced by the entire delivery cycle. A firm that records time accurately, reviews work in progress regularly, agrees payment terms early, and invoices promptly has more visibility than one that waits until a month-end administrative routine to examine outstanding work.
The UK Small Business Commissioner’s invoicing guidance recommends agreeing payment expectations, including the information a customer needs to approve an invoice, and sending the invoice promptly after the relevant work is completed. In professional services, these administrative details can affect when an engagement converts into cash.
Cash visibility also requires a forecast that is updated rather than filed away. A practical forecast can model expected receipts by client, recurring payroll and supplier payments, tax dates, debt repayments, planned hires, and investment. Scenario planning can then show the effect of a delayed project, a new employee, a large equipment purchase, or a change in demand.
KPIs should explain performance, not decorate a dashboard
There is no universal list of correct measures for every consultancy, agency, accountancy practice, architecture firm, or legal practice. The right KPIs depend on the firm’s pricing model, delivery cycle, ownership structure, and mix of recurring and project work.
However, a useful KPI has three features: it can be measured consistently, it is connected to a decision, and someone is responsible for responding to a meaningful change. For example, a rising debtor balance should prompt a review of billing information, approval processes, client communication, or disputed work. A falling utilisation measure might require a workload review rather than an immediate cost reduction.
Sector-specific reporting can provide context, but comparisons need care. A recurring advisory service, a fixed-fee project, and a long-running matter may have very different cash and margin patterns. Broad benchmarking is most useful when it helps a firm ask better questions about its own operating model.
For readers following the wider professional-services market, coverage of law firm business developments also illustrates why timely financial information is relevant to understanding how firms operate. The broader lesson applies across the sector: published figures are more informative when they are read alongside the business model, timing of receipts, funding needs, and delivery commitments.
Good controls support people and client service
Financial management is sometimes treated as a restriction on professional judgement. In practice, clear financial controls can give teams better information about priorities and capacity. A budget can show whether a planned hire is affordable. A matter or project review can identify scope changes early. A cash forecast can allow investment decisions to be considered before they become urgent.
Controls should be proportionate. Smaller firms may begin with a weekly cash review, monthly management accounts, a simple aged-debtor report, and a forecast covering the next year. Larger firms may need delegated spending authority, practice-area reporting, engagement profitability analysis, segregation of duties, and formal risk monitoring.
Technology can reduce manual effort, but software does not replace financial ownership. Automated reports are only useful if data is entered accurately, definitions are consistent, and managers act on what the reports show. A short, trusted dashboard is often more valuable than a complex system that arrives too late to influence a decision.
A practical financial-management rhythm
A professional-services firm can establish a workable rhythm without turning every meeting into an accounting exercise:
- Weekly: review bank balances, near-term receipts, urgent payments, overdue invoices, and material changes to delivery plans.
- Monthly: close the books, compare actual performance with budget, review work in progress and debtor days, and update the cash forecast.
- Quarterly: assess service-line margins, pricing, capacity, client concentration, investment plans, and financial risks.
- Annually: reset the strategy, budget for the next period, test scenarios, review financing, and confirm that controls remain appropriate.
Each review should end with decisions and owners. A forecast that identifies a cash gap is useful only when the firm decides whether to accelerate billing, adjust spending, revise hiring, seek funding, or change the delivery plan.
Financial clarity is an operating advantage
Professional expertise may win an engagement, but financial discipline helps the firm deliver it sustainably. It protects cash, reveals which work creates value, supports transparent client conversations, and gives leaders time to respond to changing conditions.
The strongest approach is not to chase every available metric. It is to build a dependable line of sight from proposal to delivery, invoice, receipt, margin, and reinvestment. When that line of sight is clear, financial management becomes part of service quality and strategic planning rather than a year-end exercise.